

First, I requested Linkedin for names to be added to the top 20, Tanzania’s fintech story is often instructed by means of cellular cash.
That is comprehensible. Mobile cash modified the nation. It introduced tens of millions of individuals into the formal monetary system, made on a regular basis funds simpler, and created the rails for a extra digital financial system led by lending, betting and retailers funds.
The remainder of the chapters on this ebook are being written by unbiased fintech corporations constructing funds infrastructure, service provider instruments, embedded finance, cross-border funds, credit score scoring, switching, stablecoins, enterprise funds, SME working methods, recurring collections, digital lending and monetary APIs.
I need to warn you that This article shouldn’t be an inventory of each fintech product working in Tanzania. It is an inventory of unbiased, Tanzania led, Tanzania first fintech corporations. That means M-Pesa, AirtelCash, PalmPay and SasaPay are excluded by design. Not as a result of they’re unimportant. They’re essential however my aim was to create area to showcase what I contemplate to be really “Tanzania’s Fintech”.
The left outs giants performed an enormous function in increasing monetary entry. Their exclusion is just a matter of scope. Because this text is targeted on a distinct query:
Which fintech corporations are being constructed from Tanzania (eg Ramani, Tembo, Selcom) or obtained their first significant crack of the market in Tanzania (eg Nala, Kuunda), not merely which fintech merchandise function in Tanzania?
The reply is extra fascinating than many individuals assume. Tanzania now has fintech corporations working throughout remittances, cost gateways, service provider methods, SME finance, switching, liquidity, stablecoins, direct debit, cross-border funds, credit score scoring, shopper finance and digital commerce infrastructure.
Tanzanian Top fintechs are backed by a mixture of native and international buyers, together with Hustle Fund, Y Combinator, DeveloPPP and Warioba Ventures. Together, they’re serving to flip a fintech adoption market right into a fintech -building market.
The Top Twenters present that Tanzania’s fintech is not nearly utilizing expertise constructed elsewhere. It is more and more about constructing the expertise ourselves.
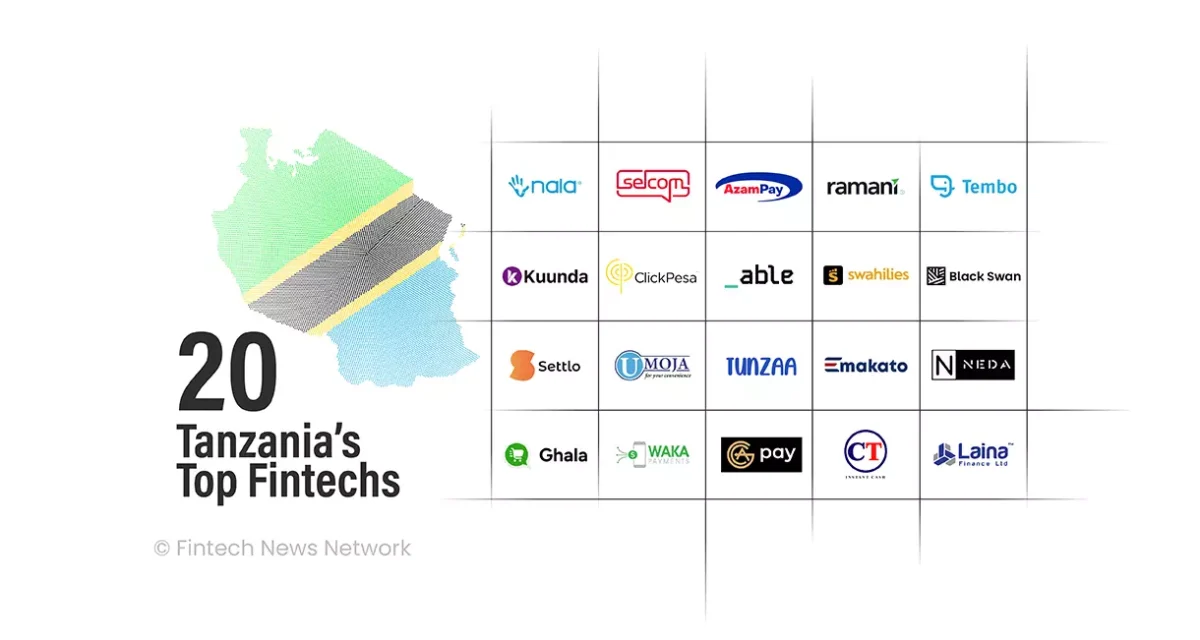
Here is the record of Tanzania’s Top 20 Fintechs as curated by Reuben Mwatosya of Cofounders Notebook and His Linkedin Community.
NALA is Tanzania’s most globally recognised fintech. What started as a Tanzanian-born remittance firm has grown into a global funds enterprise serving Africans throughout the UK, US, Europe and a number of African markets. Its shopper product helps the diaspora ship cash residence, whereas its broader infrastructure play, Rafiki, factors to a much bigger ambition: constructing cost rails for rising markets.
NALA issues as a result of it has modified what Tanzanian startups consider is feasible.It has proven that an organization with Tanzanian roots can increase critical worldwide capital, construct for international markets and compete in one of many hardest classes in fintech: cross-border funds.
Its focus space is obvious: remittances, cross-border funds and worldwide cost infrastructure. For Tanzania, NALA is greater than a fintech success story. It is a sign that domestically rooted corporations can construct for the world.
Selcom is considered one of Tanzania’s authentic fintech infrastructure corporations.Long earlier than fintech grew to become a modern phrase, Selcom was already serving to companies, banks, billers, brokers and retailers course of digital funds. Its infrastructure has supported invoice funds, service provider funds, company banking, collections, disbursements and integrations throughout the monetary ecosystem.
Selcom’s significance isn’t just that it exists. It is that it has endured and carried each financial institution, cellular cash and plenty of fintechs that got here after. In a market the place many fintech startups come and go, Selcom has remained on the centre of Tanzania’s digital funds spine for years, and it powered switching for years earlier than the nationwide swap.
Its focus space is funds infrastructure, service provider companies, collections and digital transaction processing. Infrastructure is never glamorous, however it’s foundational. That is why Selcom belongs close to the highest of this record.
Unlike many VC backed startups, AzamPay is backed by the Bakhresa ecosystem, AzamPay serves companies that want dependable methods to gather funds, automate transactions, reconcile collections and hook up with digital cost channels.
They are the one non telco cellular cash operator and Its significance comes from execution at a posh scale of a conglomerate. Tanzania’s enterprise financial system continues to be closely cash-based. Companies that make digital funds simpler for retailers, corporates and establishments are central to the nation’s subsequent monetary transformation.
AzamPay’s focus space is service provider funds, cellular cash and digital commerce infrastructure. Its profile has additionally moved past Tanzania, with global recognition serving to place it as one of many nation’s most seen cost infrastructure corporations.
Ramani sits on the intersection of provide chain, knowledge and embedded finance. The firm digitises micro-distribution and shopper items provide chains, serving to distributors, manufacturers and retailers perceive gross sales, stock and money movement extra clearly. That working knowledge can then turn into the muse for credit score and dealing capital.
Ramani is essential as a result of it reveals one of the highly effective instructions in African fintech: finance embedded inside actual commerce. Instead of asking small companies to stroll right into a financial institution with restricted data, Ramani helps create the data first.
That makes retailers extra seen, extra measurable and extra financeable. Its focus space is supply-chain finance, service provider knowledge, working capital and embedded finance.
TemboPlus is constructing cost and banking infrastructure for companies. Its API-led mannequin helps corporations embed monetary companies into their very own merchandise. That contains funds, collections, wallets, accounts, cellular cash integrations, remittances and different monetary infrastructure.
TemboPlus issues as a result of the subsequent wave of fintech won’t solely be about standalone shopper apps. It will even be about infrastructure that permits different corporations to launch monetary companies sooner.
Every market, logistics firm, lender, service provider system, college platform, subscription firm or enterprise software program product could finally want embedded funds or monetary options. Tembo is constructing for that world.
Kuunda is among the most essential embedded liquidity fintechs linked to Tanzania largest credit score product (Songesha on Mpesa). Its mannequin focuses on short-term liquidity merchandise akin to cellular cash float loans, airtime float, service provider money advances, inventory financing and working-capital options.
These merchandise resolve a really actual drawback in African commerce: brokers and retailers typically lose transactions as a result of they run out of float or working capital.Kuunda’s power is that it embeds credit score the place transactions already occur.
Rather than forcing prospects right into a separate lending journey, it locations liquidity contained in the platforms and channels retailers already use.
Probably the second oldest Fintech after Selcom, Click onPesa is a enterprise funds platform centered on serving to corporations handle funds extra effectively, plus they had been very early in crypto and issued the first TZS stablecoin on stellar.
Its core merchandise serve SMEs, corporates, MFIs and organisations that must deal with collections, payouts, cost automation and reconciliation throughout a number of channels.
Click onPesa belongs on this record as a result of enterprise funds are nonetheless one of many least glamorous however most essential they write about the challenges and opportunities
With strong partnership w DTB, Airtel and Vodacom, Credable is an embedded finance and digital banking infrastructure firm with sturdy Tanzanian roots.
It works with banks, telecoms and companies to launch credit score and financial savings merchandise by means of present buyer channels. Credable issues as a result of distribution is among the hardest issues in monetary companies.
Instead of attempting to amass each buyer immediately, Credable permits establishments and platforms that have already got prospects to supply monetary merchandise. Its focus space is embedded finance, digital banking infrastructure and credit score enablement.
Swahilies is among the strongest SME-focused fintech corporations in Tanzania. It offers a monetary working system for small companies, combining instruments for stock, gross sales, funds, analytics and enterprise operations.
Its give attention to SMEs is essential as a result of Tanzania’s financial system is constructed on small and casual companies that usually lack clear data, structured cost histories and entry to formal finance.
Swahilies issues as a result of SME digitisation is a fintech drawback NOT a software program drawback. Once a small enterprise has digital data, it turns into simpler to supply funds, working capital, financial savings, insurance coverage and different monetary companies.
Its focus space is SME working methods, enterprise administration, funds and service provider knowledge. Swahilies is greater than a enterprise device. It is a part of the information layer for SME finance together with cross border funds, credit score and native funds.
Black Swan is an AI-driven fintech centered on different credit score scoring and monetary inclusion lately recognised by Bloomberg.
Its work is essential as a result of Tanzania, like many African markets, nonetheless has a significant credit score info hole. Many people and small companies are economically lively however invisible to conventional lenders as a result of they lack formal credit score histories.
Black Swan addresses that hole through the use of different knowledge and AI-driven scoring to assist lenders perceive danger extra successfully.
Its momentum has additionally obtained continental recognition, with Black Swan named amongst African startups to observe. Its focus space is different credit score scoring, consent-based monetary knowledge sharing, lending intelligence and monetary inclusion.
UmojaSwitch is considered one of Tanzania’s most essential monetary infrastructure gamers. It offers shared digital cost and fund-transfer infrastructure that connects banks and different financial-service suppliers. Its function will not be as seen as a shopper app, however it’s deeply essential.
A monetary ecosystem wants switches, rails and interoperability. Without these layers, banks, retailers, ATMs, playing cards and suppliers can’t join effectively.
Its focus space is switching, interoperability, cost infrastructure and monetary connectivity. UmojaSwitch belongs on this record as a result of fintech shouldn’t be solely concerning the corporations customers see. It can be concerning the infrastructure that makes transactions doable behind the scenes.
Tunzaa sits within the shopper finance and save-to-buy class. Its mannequin helps prospects plan purchases, save towards merchandise and entry items in a extra structured manner. This issues as a result of many customers can’t afford massive purchases upfront, but in addition don’t wish to fall into irresponsible debt. The save-now-buy-later mannequin is a vital different to pure lending.
Tunzaa’s focus space is shopper finance, structured financial savings, affordability and commerce. It belongs on this record as a result of Tanzania wants extra fintech merchandise that assist individuals plan, save and purchase responsibly.In markets with irregular earnings, affordability isn’t just about credit score. It can be about self-discipline, timing and construction.
Cofounded and led by the cofounder of Laina Finance, SoloCodes is constructing E-makato, a direct debit answer for recurring subscriber and utility funds.
This is a vital fintech class as a result of many companies in Tanzania nonetheless wrestle with recurring collections. Subscriptions, college charges, insurance coverage premiums, lease, utilities, mortgage repayments and repair payments typically rely upon handbook follow-ups, cellular cash prompts or irregular customer-initiated funds.
E-makato addresses that hole by serving to companies accumulate recurring funds extra predictably. Direct debit infrastructure could not sound as thrilling as shopper apps or remittances, but it surely is among the final lacking layers in Tanzania’s cost ecosystem.
The firm is constructing nTZS, a Tanzanian shilling-pegged stablecoin. This locations it on the frontier of managed experimentation with blockchain-based funds and digital property within the nation.
In rising markets, regulated digital cash might doubtlessly help sooner settlement, programmable funds, cross-border and new monetary infrastructure.
NEDA Labs belongs on this record as a result of it’s pushing the boundary of what fintech regulation and innovation can appear like, that’s greater than stablecoin as a class.
Its inclusion issues as a result of Tanzania’s fintech ecosystem is not restricted to cost gateways and cellular cash integrations. The ecosystem is starting to incorporate extra superior infrastructure, regulated experimentation and expertise merchandise that may help monetary companies in new methods.
Ghala’s focus space is monetary infrastructure, sandbox innovation and digital monetary expertise. The significance of merchandise like Ghala shouldn’t be solely what they do as we speak. It is what they sign. They present that founders are starting to construct for regulated monetary innovation from the beginning, not as an afterthought. That is a wholesome signal for the market.
WakaPay is an outward cross-border funds platform centered on serving to customers and companies make funds throughout African markets.
Its mannequin is very related as a result of Tanzania is deeply linked to regional commerce, diaspora motion and cross-border commerce. Tanzanian customers, Kenyan retailers, regional merchants and cellular cash customers typically want sooner and less complicated methods to maneuver worth throughout borders.
WakaPay’s focus space is cross-border cellular cash, service provider funds and intra-African commerce. This is among the largest alternatives in African fintech. Trade already strikes throughout borders. People already transfer throughout borders. Families already transfer cash throughout borders.
Recently licensed GCA Pay is among the Old fintech corporations in Tanzania by volumes and worth they deal with. Built underneath Goldcavern Associates, it sits on the intersection of FX, cross-border settlement and enterprise monetary infrastructure.
Its positioning is essential as a result of Tanzania is more and more changing into a settlement and commerce hall market, particularly for companies transferring cash between Africa, Asia and different international markets. Companies don’t solely want cost assortment. They want liquidity, compliance, FX, reconciliation and dependable settlement throughout a number of rails.
Its focus space is cross-border funds, treasury, FX, provider funds, collections, payouts and enterprise settlement infrastructure. GCA Pay is greater than a cost gateway. It is a part of the infrastructure layer for African commerce, stablecoin-powered settlement and regional enterprise funds.
Powered by crowdfunding, CashMe Tanzania represents the digital credit score and short-term finance aspect of the ecosystem. Credit stays one of many largest gaps in Tanzania’s monetary system. Many individuals and small companies want entry to quick, versatile and accountable financing, however conventional channels might be gradual, paperwork-heavy or inaccessible.
CashMe Tanzania’s focus space is digital lending and crowdfunding which is area of interest however fascinating sufficient to showcase what is feasible at scale. Digital lending can create actual worth when it’s clear, truthful and accountable.
Probably the OG of smartphone lending in Tanzania, Laina Finance focuses on digital lending and versatile financing for Tanzanian customers and companies.
Its inclusion is essential as a result of credit score entry stays one of many largest gaps in Tanzania’s monetary system and Laina was one of many pioneers within the area. Laina represents the digital credit score layer of the ecosystem. Its focus space is digital lending, instalment finance and versatile shopper or enterprise financing.
This class is central to fintech as a result of funds alone don’t resolve monetary inclusion. People and companies additionally want higher methods to entry capital, clean earnings gaps and finance helpful property.
Tanzania’s fintech ecosystem shouldn’t be but as massive or globally seen as Kenya or South Africa. But it’s extra fascinating than many individuals realise. This record reveals a market transferring past the primary layer of cellular cash right into a broader fintech stack:
Remittances, funds infrastructure, service provider instruments, embedded finance, switching, credit score scoring, SME working methods, enterprise funds, stablecoins, direct debit, cross-border funds, digital lending, shopper finance and controlled sandbox innovation.That is a a lot richer story. The first wave of Tanzania’s digital finance was constructed by telcos, banks and enormous cost operators.
The subsequent wave is being constructed by fintech entrepreneurs, infrastructure corporations and embedded-finance platforms that perceive native issues deeply. And probably the most thrilling half is that many essential classes are nonetheless broad open.
Tanzania wants extra corporations constructing recurring cost infrastructure. Subscriptions, insurance coverage premiums, college charges, lease, utilities, mortgage repayments and enterprise memberships mustn’t rely solely on handbook reminders or customer-initiated funds.
Reliable direct debit infrastructure can unlock subscription companies, cut back assortment prices and assist service suppliers plan money movement higher. This is among the least glamorous however most essential fintech gaps.
Small companies energy Tanzania’s financial system, however many nonetheless lack entry to quick, truthful and versatile credit score. The alternative shouldn’t be solely to lend. It is to construct higher underwriting fashions utilizing gross sales knowledge, stock knowledge, funds knowledge, provider relationships and transaction historical past. The subsequent technology of SME lenders won’t win by copying previous banking fashions. They will win by understanding actual enterprise behaviour.
Many retailers nonetheless function in cash-heavy environments. Tanzania wants extra innovation in service provider buying, QR funds, low-cost acceptance, offline funds, reconciliation and settlement. The aim mustn’t merely be to digitise transactions. The aim must be to make digital funds simpler than money.
Tanzania sits in a area the place commerce, journey and household networks cross borders every single day. Yet cross-border funds stay too gradual, too costly or too sophisticated for many individuals and small companies. There is room for extra gamers constructing regional cost rails between Tanzania, Kenya, Uganda, Rwanda, Zambia, Malawi, DRC and past.
Insurance penetration stays low, however the want is big. Health, crop, asset, funeral, motor and microinsurance merchandise can turn into extra accessible if distribution, pricing, claims and funds are digitised correctly. Tanzania wants extra insurtech gamers that may make insurance coverage easy, reasonably priced and trusted.
As digital finance grows, so do fraud, compliance and id challenges. Tanzania wants extra fintech infrastructure round KYC, KYB, fraud detection, transaction monitoring, consent-based knowledge sharing and safe id verification. These merchandise could not at all times be seen to customers, however they’re important for belief. Without belief, fintech can’t scale.
The way forward for credit score, financial savings, insurance coverage and personalised monetary companies will rely upon higher knowledge portability and user-controlled monetary knowledge. Tanzania wants extra gamers constructing the rails for secure, permissioned and controlled monetary knowledge sharing. This might assist lenders make higher selections, assist prospects entry higher merchandise, and assist monetary establishments serve customers extra intelligently.
The way forward for Tanzanian fintech won’t be gained by one firm. It can be constructed layer by layer. One firm will construct cross-border rails. Another will construct service provider methods. Another will construct direct debit. Another will construct credit score scoring. Another will construct stablecoin settlement.
Another will digitise SMEs. Another will join banks, wallets and companies behind the scenes. That is how ecosystems are constructed. Not by means of one tremendous app. But by means of many specialised corporations fixing arduous, particular issues.
Tanzania already has the primary technology of significant fintech builders. The subsequent query is whether or not the nation can produce the subsequent 50. Because the chance shouldn’t be small. It is huge. Tanzania doesn’t simply must undertake fintech. Tanzania can construct fintech.
This article first appeared on https://reubenmars.substack.com/
Featured picture: Edited by Fintech News Africa, primarily based on picture by graphic_titan through Magnific


