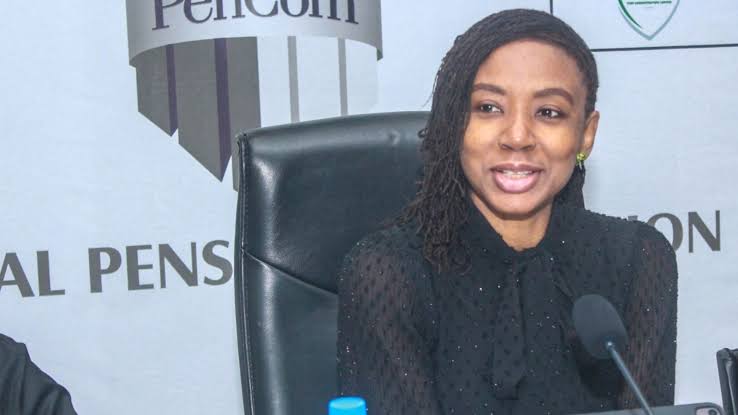
The National Pension Commission (PenCom) has disclosed that solely 14 of Nigeria’s 36 states are at present paying up on their pension obligations, highlighting persistent funding gaps within the nation’s public-sector pension system.
The Director-General of PenCom, Omolola Oloworaran, made this recognized throughout an interview on Arise TV on Monday.
She acknowledged that a number of state governments have been nonetheless struggling to fulfill their pension commitments regardless of ongoing engagements with the fee.
State pension obligations stay a problem
Speaking on the challenges dealing with retirees, the PenCom boss acknowledged that state-stage pension administration remained a priority, significantly as some governments continued to wrestle with their pension commitments.
She stated the fee was working with state governments to handle excellent obligations, noting that some had begun making funds however nonetheless had substantial floor to cowl.
- “We have 14 states that are paying up. But 14 out of 36 states. And, some states are doing very badly,” she stated.
Her feedback got here amid questions on complaints from retirees who claimed that they had not acquired their pensions and gratuities years after leaving public service.
The PenCom DG distinguished between federal and state pension preparations, explaining that federal retirees below the previous Defined Benefit Scheme are managed by the Pension Transitional Arrangement Directorate (PTAD), whereas workers retiring below the Contributory Pension Scheme are regulated by PenCom.
Nairametrics had earlier reported on the sluggish tempo of pension reform implementation throughout Nigerian states. In July 2026, this publication reported that Oloworaran had disclosed that only eight of the 36 states have been working the Contributory Pension Scheme in compliance with the legislation.
Federal Government clears pension liabilities
Oloworaran stated the Federal Government had addressed excellent obligations below the Contributory Pension Scheme via a N758 billion intervention bond accepted by President Bola Tinubu’s administration to clear accrued pension liabilities.
According to her, the intervention was meant to settle excellent pension obligations owed to retirees below the scheme.
She defined that following the introduction of the Contributory Pension Scheme in 2004, federal workers who retired earlier than June 2004 and people who had three years or much less remaining earlier than retirement have been lined by the previous Defined Benefit Scheme.
Those retirees are managed by the Pension Transitional Arrangement Directorate (PTAD), which was established below the Pension Reform Act 2014 to deal with pension funds to federal authorities retirees below the earlier association.
The DG stated she was not conscious of excellent federal pension funds below both association, though she acknowledged that delays generally occurred below PTAD.
She added that the fee was keen to analyze particular complaints from affected retirees.
State pension reforms stay sluggish
The newest disclosure comes amid broader considerations in regards to the implementation of pension reforms and the settlement of retirement obligations by state governments throughout Nigeria.
Earlier, in April 2026, the National Association of Retirees of State (*14*) threatened a nationwide protest if state governors failed to review pension payments in line with existing labour laws. The affiliation cited irregular and insufficient pension funds throughout a number of states.