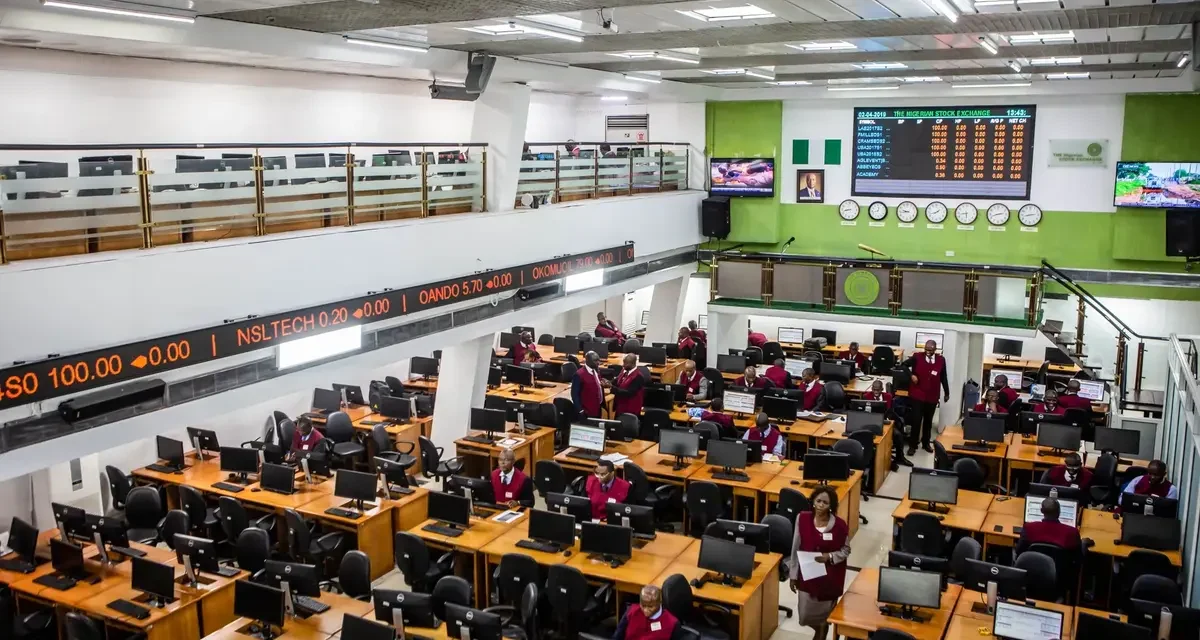

The NGX All-Share Index not too long ago breached the 250,000-mark, triggering a profit-taking pattern in massive blue-chip counters. The NGX All-Share Index shed 1.98% to shut at 249,710.59 factors (a decline of 5,052.22 factors) on Thursday, November 5, 2026.
Nigerian inventory market valuation declined by N3.3 trillion to settle at N162.12 trillion, and year-to-date return momentarily softened to 60.47%, whereas market breadth turned unfavourable with 20 gainers to 36 decliners.
The market noticed the most important loss by Dangote Cement, down 10%, which dragged the NGX Industrial Index down 7.14%; UACN-7.85% (-7.85%) dragged the Consumer Goods Index down 1.12%; FIRSTHOLDCO-2.40% (-2.40%) and STANBIC-0.85% (-0.85%) pulled the
Banking Index down by 0.66%; the Insurance Index went down 2.51%, marking the heaviest promoting session within the sector.
- Although the market declined, turnover remained excessive at 29.55 billion, buying and selling throughout 33,199 offers, pushed by substantial liquidity flows in Stanbic IBTC and Access Holdings (ACCESSCORP). Macro dangers like competing for high-yield fastened revenue charges are engaging to asset managers for short-term tactical rebalancing.
There is a squeeze on current blue chips’ liquidity, profit-taking, and a correction under the 250,000-level available on the market. Domestic and international institutional liquidity sucked out of secondary market blue-chips to pre-fund IPO (preliminary public providing) subscriptions earlier than the two.15trn Dangote Refinery IPO closes in October.
The total trade market capitalization will probably shoot as much as virtually 230 trillion as quickly as the enormous capital injection is anticipated to get listed on NGX (anticipated in December)
- Key demand zone for Nigerian stocks turns under the upswing (248,500 – 250,000). A breakout above 255,000- 256,950 guidelines out a deeper correction if it closes above 250K on the day by day chart. Secondary demand zone (242,000 – 245,000): The secondary demand zone aligns with the short-term exponential shifting averages (20-day / 50-day EMA zone).
Institutional demanders are likely to re-engage close to this structural consolidation zone. 1st upside resistance zone (251,200 – 253,000): The latest all-time excessive upside resistance zone. Validating 251,200 and a rise in day by day quantity sign a revival of the first bull pattern.
Daily momentum indicators similar to RSI & MACD metrics additionally point out short-term overbought reduction, which tends to unwind as we construct medium-to-long-term technical tendencies.
- Tier-1 Banks (GTCO, Zenith, Access Corp) and Industrial Giants (BUA Cement, Dangote Cement) noticed sturdy promote strain as institutional funds booked income amid the bullish rally. Capital raises on NGX persist, attracting liquidity whereas fundamentals enhance (long-term) and steadiness sheet resilience.
- Capital calls take in provide no less than quickly on the trade. Competitive yields from fastened revenue (like NTB and OMO payments) lead to tactical asset managers shifting from absolutely priced equities to cash market investments.
Valuation help stays on the low finish of the spectrum resulting from company earnings energy in banking and telecommunications, offering a valuation ground for long-term buyers.
Short-Term Traders: Wait for stabilization of candles (bullish engulfing, lengthy decrease wicks, and so forth.) close to the help zone of 248,500 – 250,000 earlier than moving into contemporary longs. For Long-Term Value Investors: Market corrections present compelling risk-to-reward entry alternatives to purchase diversified blue chips which can be oversold of their dip.