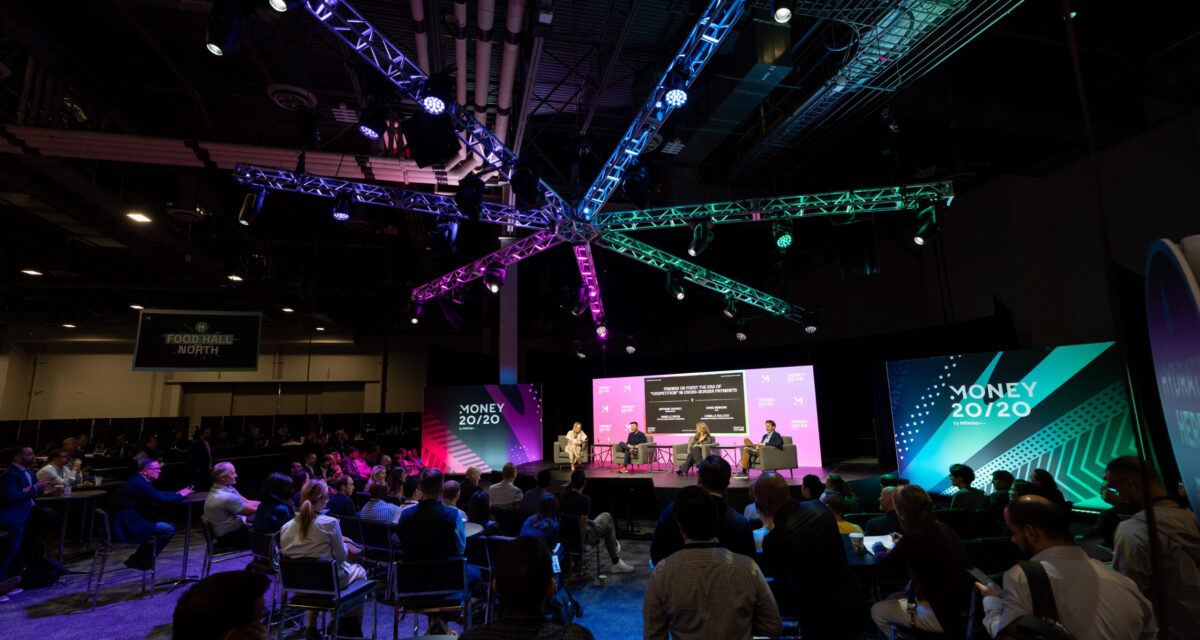

Las Vegas spent three days asking who carries the danger when cash strikes itself. On the final morning, the first federal stablecoin rule gave a part of a solution.
For three days in Las Vegas, the periods I recorded stored returning to at least one query: when cash strikes itself, who carries the danger? Day one requested it about stablecoins and AI brokers. Day two confirmed the trade writing its personal solutions into requirements, certificates and code. On Wednesday, the closing half-day, a regulator wrote a part of the reply down. Just a few hours earlier than the Money Hall opened for the final time, the Office of the Comptroller of the Currency (OCC) turned the first company to finalise its rule below the GENIUS Act.
The rulebook lands on the final morning
The OCC’s rule units out how banks and non-bank corporations can turn into permitted fee stablecoin issuers. Issuers should maintain reserves that absolutely again the cash in circulation and can typically have to fulfill redemptions inside two enterprise days, with requirements for custody, capital, audit and overseas issuers alongside. It takes impact in January, and the regulator will say individually when it begins accepting purposes. Anti-money laundering and sanctions obligations are left to later rulemaking with the Treasury.

The argument that follows might be about yield. The rule retains the ban on issuers paying holders curiosity merely for holding a stablecoin, but it surely drops the proposal’s presumption that sure preparations with associates and third events are makes an attempt to get spherical that ban. The OCC will decide rewards programmes case by case and retains the energy to behave in opposition to evasion. Comptroller Jonathan Gould referred to as it a transparent, sensible framework. Banks see a door left open for platforms to pay rewards that draw deposits away from neighborhood lenders, and the American Bankers Association was fast to criticise the rule, The Block reported.
That places a date on the contest the present spent the week taking aside. On Tuesday Citi‘s Ryan Rugg stated tokenised deposits and stablecoins had been “an and”, and Coinbase‘s Shan Aggarwal argued that the blocker is now coordination between custodians, clearing homes and banks, not expertise. A federal rulebook is one piece of that coordination. The different piece continues to be to come back: per week earlier than the present, FDIC Chairman Travis Hill stated the company could have extra work to do on tokenised deposits as soon as the GENIUS Act guidelines are written, together with find out how to resolve a failed financial institution whose deposits transfer at weekends.
Controls written into the fee
The legal responsibility query didn’t anticipate the regulator both. Visa introduced on Wednesday new controls for business card funds: a test that cash goes to the provider it ought to, 3-D Secure authentication for digital card customers, and limits a enterprise can set on spend, service provider class, location and timing. The fee controls can be found now to eligible issuers; the provider validation and authentication instruments are in pilot and due for basic launch in 2027. The similar announcement folded in Tuesday’s stay pilot with BILL and Billtrust, during which trusted AI brokers pay permitted invoices by means of provider portals utilizing tokenised credentials as an alternative of shared logins.
Ninth Wave, which connects banks and credit score unions to fintech apps and aggregators, utilized the similar considering to account knowledge. Its new Agentic Control Layer ties each agent to a registered, accountable operator earlier than it might join, checks the buyer’s consent on every request quite than as soon as per session, and masks account numbers earlier than they attain the AI mannequin. The first launch is read-only, with cash motion on the roadmap.
Set beside Monday’s launches, from Mastercard‘s risk score for stablecoin payments to Evervault‘s short-lived agent tokens on Tuesday, the pattern is hard to miss. Day one asked who holds the bag. By the close, the industry’s working reply was that no one fingers an agent the bag with no named operator, a restricted mandate and a document of each request. On legal responsibility itself, Hill stated on Tuesday that the deeper questions are most likely exterior the FDIC’s purview.
Trust as the closing argument
The closing morning’s programme learn like a abstract of the week. The Meridian Stage opened with the chief advertising and marketing officers of Early Warning, JPMorganChase and PNC on the case that belief is a progress technique quite than a tender metric, adopted by a session on how an explainable AI deployment received by means of an audit. On the Intersection Stage, Intercontinental Exchange vice chairman Michael Harris and DTCC‘s Jason Emery had been billed to debate taking digital belongings out of the sandbox and into core operations, and Siegel+Gale introduced new analysis arguing that complexity, not a scarcity of innovation, is what erodes belief in monetary companies.
A session on small enterprise finance made the similar level from the buyer’s aspect: for an proprietor, a funding product decides whether or not payroll clears. That is the buyer the week stored coming again to, the one who doesn’t care which rail carries the cash. Stripe‘s Neetika Bansal stated on Tuesday that prospects not often ask for stablecoins any extra; they ask for cross-border funds that arrive. On Monday, Alex Garn of Borderless gave the one-word model of what the trade has to get proper: invisible.
The Fintech Times in Las Vegas
My recorder ran on the Meridian, Intersection and Exchange levels on Monday and Tuesday, and 4 strains from these periods sum up the week. Ann Johnson, who runs safety options at Mastercard, set the phrases on Monday: “the thing that allows innovation to scale is trust.” Hill, describing the standard-setting physique the FDIC has been serving to banks and fintechs design for vetting third events, pressured that it might be led by the trade and that “this would be completely voluntary”. Bansal referred to as stablecoins “agent native money”. And Aggarwal, requested the place tokenisation finally ends up by 2030, hoped the class merely disappears: “I think we just talk about assets.”
Read collectively, they describe the shift from Riyadh and Miami to Las Vegas. The expertise arguments are largely settled. What stays is who vouches for the contributors, who units the requirements they’re held to, and whether or not the buyer ever must know.
What the subsequent conversations might be
Three questions go away Las Vegas unanswered. The first is rewards. The OCC has chosen case-by-case judgement over a blanket presumption, the banks have stated they don’t prefer it, and the different businesses nonetheless have their very own GENIUS Act guidelines to complete. With the wider market construction invoice stalled in the Senate, the line between a stablecoin reward and a deposit charge might be drawn rule by rule and case by case.
The second is who accredits an agent. Visa’s Trusted Agent Protocol, Ninth Wave’s registered operators and the FDIC’s proposed voluntary requirements physique for financial institution companions are all variations of the similar thought: a named get together that vouches for whoever, or no matter, is transferring the cash. Whether these schemes converge or every community retains its personal register will determine how a lot friction an agent meets crossing from one to the subsequent.
The third is the transfer from pilot to revenue and loss. Visa’s provider instruments attain basic launch subsequent yr, Ninth Wave’s layer begins read-only, and the OCC has but to open its software window. The present ended on the query of working these methods at scale, and the solutions will are available in the quarterly numbers quite than on stage.
The subsequent chapter of Money20/20 USA. Money20/20 USA is transferring to the Las Vegas Convention Center (LVCC) and Resorts World on October 19-21, 2027. Take a first look at the future of money.
AI stage 3 of 5: AI-drafted from revealed sources our editor chosen, linked in the piece; fact-checked and signed off by Mark Walker, Editorial Director. What the levels mean