
In April, Flutterwave, a pan-African fintech unicorn, secured a national microfinance banking licence by means of its acquisition of open banking startup Mono. It joined a rising group of Nigerian fintechs shifting into regulated banking. In January, Paystack acquired Ladder Microfinance Bank, whereas Moniepoint secured a microfinance banking licence in 2025.
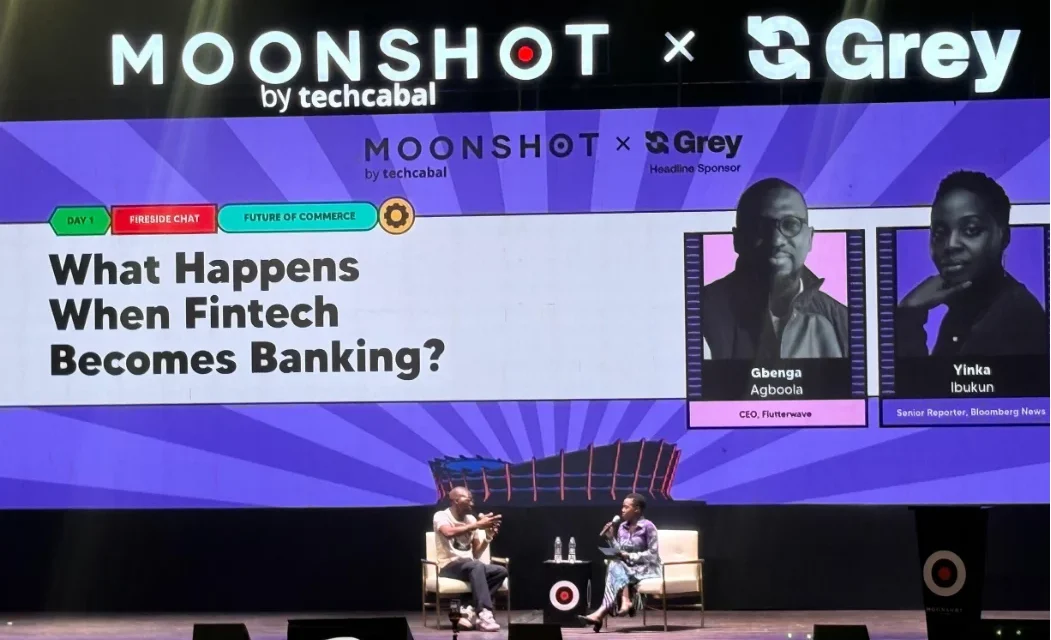
African fintechs are shifting from solely processing funds to holding deposits, offering credit score and providing different banking companies. For Olugbenga “GB” Agboola, cofounder and CEO of Flutterwave, African fintechs are turning into banks as a result of funds alone are not sufficient.
Speaking at Moonshot in Lagos on Wednesday, Agboola mentioned Flutterwave’s determination to get hold of a nationwide microfinance banking licence was pushed by the necessity to management extra of the infrastructure behind its funds enterprise.
“What we’ve seen is you cannot provide a great payment experience if you don’t control the entire stack, or at least a big piece of the stack,” Agboola mentioned. “And in most of those large stacks, it’s easy to source a third party who does not share the same level of focus that you have.”
Flutterwave has processed more than $40 billion in lifetime funds, giving it a big current funds enterprise to construct its banking technique round. The firm has additionally mentioned that greater than 2 million companies use its platform. Agboola mentioned the dimensions of the funds enterprise additionally uncovered the restrictions of relying on third-party monetary establishments. If a accomplice financial institution goes down, elements of Flutterwave’s cost infrastructure can go down with it.
“We didn’t choose to do banking for the sake of banking,” Agboola mentioned. “We chose to do banking to create more depth for our customers.”
The transfer into banking additionally offers Flutterwave a path into lending, an space the place the corporate believes its current transaction information might give it a bonus. Agboola mentioned Flutterwave can see how companies and customers use its cost infrastructure, together with when prospects try transactions with out adequate funds or when companies have receivables however want working capital instantly.
However, Flutterwave’s lending technique isn’t instantly targeted on turning into a mass-market lender. Agboola mentioned the corporate is beginning with liquidity and working-capital infrastructure, together with pre-funding payouts for corporations that want to make funds in Africa earlier than receiving their very own funds.
In June, Flutterwave raised a Series E round at a $3.25 billion valuation after Ripple invested an undisclosed quantity within the firm. The partnership additionally built-in Ripple’s RLUSD stablecoin into Flutterwave’s cost infrastructure.
The deal was half of a bigger stablecoin technique that adopted the corporate’s partnership with Turnkey and Nuvion to launch stablecoin balances and embedded wallets supporting USDC and USDT. In June, it additionally partnered with Tempo to construct stablecoin-powered cost and settlement infrastructure for African funds.
Agboola mentioned the corporate is seeing companies encounter stablecoins as a sensible cost choice, significantly when paying worldwide suppliers.
“We’ve built what I call the largest deployment of stablecoins in Africa, where we support all the blockchains and stablecoins,” Agboola mentioned.
The growth is going on towards a backdrop of rising competitors between fintechs and conventional banks for management of shoppers’ monetary relationships. Flutterwave says it at present operates throughout greater than 35 international locations and has greater than 50 international licences.