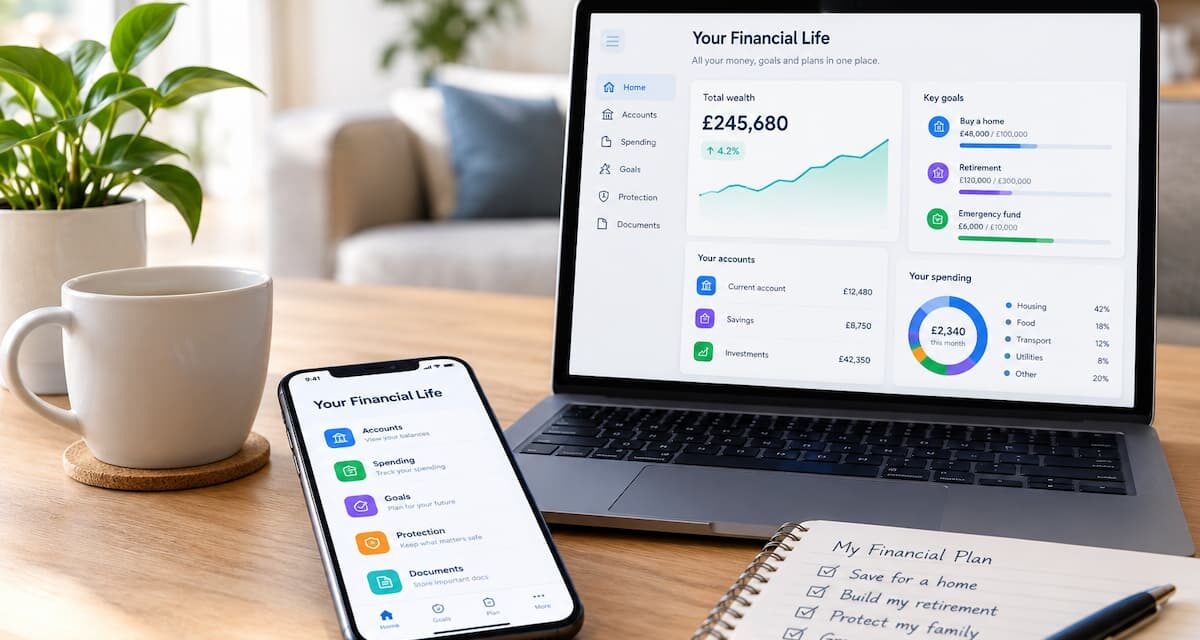

Capsafa, a UK fintech startup based by monetary providers know-how entrepreneur Dan Yorke, launched in September 2026 with a free platform designed to assist households consolidate information of their accounts, investments, pensions, insurance coverage insurance policies and property in a single place. The product is self-funded and the core service, together with an Executor Pack that summarises a consumer’s recorded monetary affairs, is positioned as completely free.

Yorke, who has labored in monetary providers know-how since 1998 and runs a mortgage and enterprise finance brokerage, stated he constructed the platform after repeatedly watching lacking paperwork delay consumer purposes. “Every provider gives its customers a view of the product they hold with them,” he stated. “But keeping track of how it all fits together is still largely the customers’ job. As they change jobs, move house and take out new policies, it becomes increasingly difficult to manage.”
The platform doesn’t join on to monetary accounts or require login credentials. Instead, customers add paperwork manually or word the place originals are held, and set renewal and evaluation reminders. Data is encrypted in transit and at relaxation utilizing AES-256 encryption, two-factor authentication is obligatory on each login, and the corporate says it doesn’t promote consumer knowledge. Before launch, Capsafa underwent penetration testing by AppSecure Security, a CREST-approved agency, and holds UK government-backed Cyber Essentials certification.
Capsafa commissioned a OnePoll survey, masking financial savings accounts, investments and money owed, which discovered that 25% of UK adults weren’t assured their household might find and perceive all of their monetary affairs with out their assist. The firm is utilizing that determine to border the business case for its organiser.
The partnership mannequin
The go-to-market technique is constructed on skilled distribution fairly than direct shopper acquisition. Capsafa is actively looking for partnerships with mortgage brokers, monetary advisers, accountants and will-writing corporations, which it expects will introduce the organiser to shoppers at moments when monetary organisation is already entrance of thoughts, similar to a remortgage or an estate-planning evaluation. Revenue is deliberate by means of non-obligatory premium options and business partnership preparations, although no pricing or companion names have been disclosed at this stage.
The mannequin is notable in a market the place open banking and account-aggregation platforms have, for a number of years, competed for the identical household-organisation use case. Products from established suppliers within the aggregation area usually require API-based connections to monetary establishments, pulling dwell balances and transaction knowledge. Capsafa takes a intentionally lighter strategy: a guide, document-centric organiser that explicitly avoids holding account credentials or appearing as a monetary aggregator. That distinction might scale back regulatory floor space but in addition limits the real-time utility the platform can provide in contrast with linked options.
Market context
The UK monetary wellbeing and household-organisation phase has attracted a number of entrants, from open-banking-powered apps to legacy financial-planning instruments. The differentiator Capsafa is betting on is simplicity of compliance posture and the skilled middleman channel. By not aggregating dwell monetary knowledge, it sits exterior the instantly supervised perimeter for account info providers beneath UK Payment Services Regulations, which might decrease the regulatory value of onboarding dealer and adviser distribution companions.
The rapid query is whether or not skilled companions will combine the referral into their consumer journey constantly sufficient to construct family adoption at scale. Capsafa doesn’t but have named companions on report, and the self-funded mannequin means the runway for that distribution effort is constrained till premium income or partnership charges start to materialise.
AI stage 1 of 5: written by Darlyn Ho; AI helped with tone, construction or wording; edited and signed off by Mark Walker, Editorial Director. What the levels mean